"When Sri Lankans buy and sell USDT between each other locally, does the national fiat actually leave the country, or are we just moving money between ourselves?"
It is a question that sits at the intersection of monetary economics, crypto mechanics and developing-world financial realities. The answer is more layered than most people expect, so let us work through it carefully.
// Section 01
What actually happens in local P2P trading
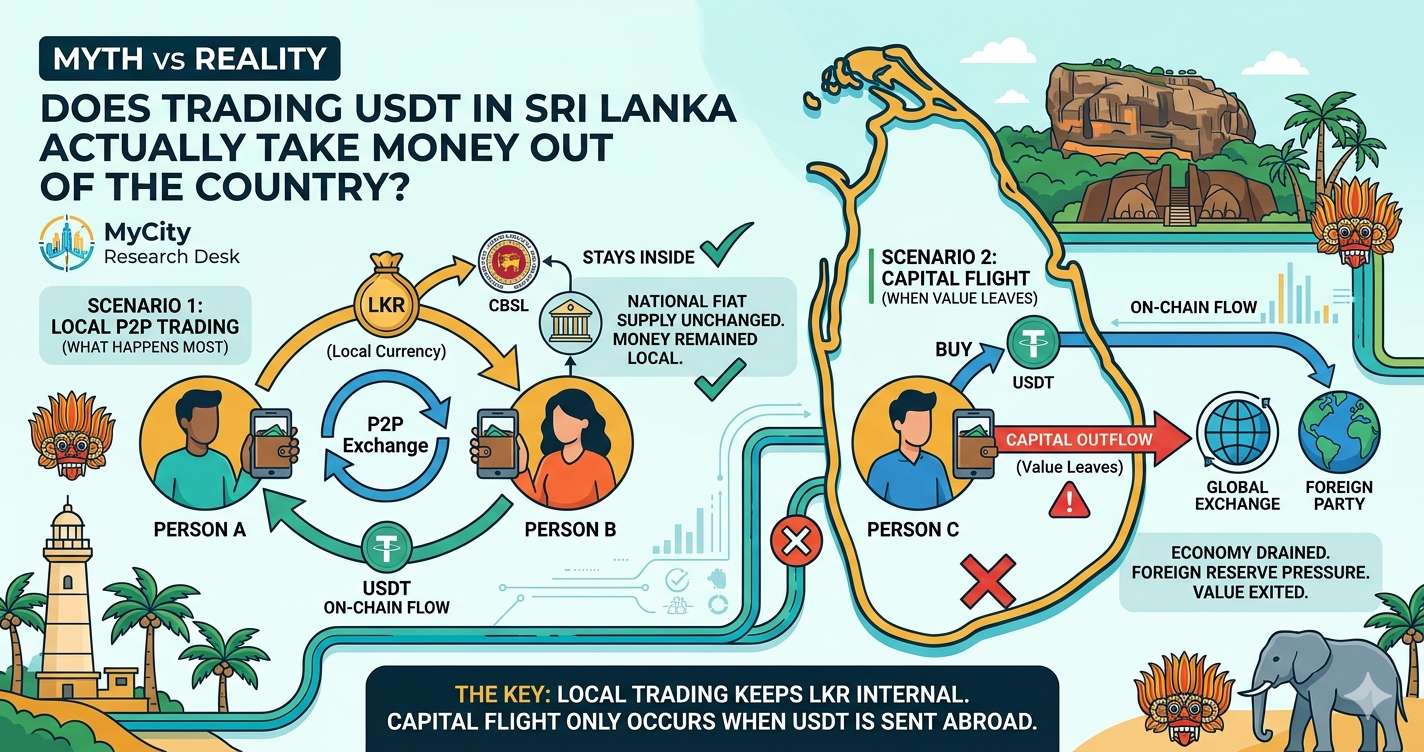
Imagine two people inside Sri Lanka. Person A has LKR sitting in a local bank account. Person B already owns USDT. Person A wants to buy 100 USDT from Person B.
- Crypto ownership changed. Person A now holds the USDT.
- Fiat ownership changed. Person B now holds the LKR.
- National fiat supply did not shrink. The same rupees are still inside Sri Lanka.
- No US dollars left the banking system. No foreign reserve was touched.
This is the critical insight most casual observers miss. The same amount of LKR still exists inside Sri Lanka. It simply moved from Person A's bank account to Person B's. At a purely local level, two Sri Lankans, two wallets, one trade, the national fiat supply is unchanged. What changed is who holds the USDT and who holds the LKR.
It runs against the intuition that "buying a dollar-pegged asset means the dollar went somewhere." In a fully domestic P2P trade, it did not, at least not yet.
// Section 02
USDT as a "Layer 2" on fiat rails
This brings us to a framing increasingly used by economists who study developing economies: stablecoins working as a Layer 2 liquidity network sitting on top of fiat infrastructure.
// The emerging dual-layer economy

OVERLAY LAYER  = Crypto liquidity network (USDT)
  → peer-to-peer settlement   → digital savings
  → cross-border transfers    → trading capital

BASE LAYER     = National fiat system (LKR)
  → tax collection            → legal tender
  → salary payments           → banking infrastructure
  → central bank control
Local banks still process deposits, withdrawals and transfers, and the national fiat system still anchors everything. But the "store of value" and "trading asset" layer is shifting toward USDT, operating in parallel above the fiat rails rather than replacing them.
The analogy comes from crypto itself. Bitcoin's Lightning Network is a Layer 2 built on Bitcoin to make transactions faster and cheaper without changing the base protocol. In developing economies, USDT increasingly works the same way on top of national fiat.
// Section 03
When crypto does affect the national currency
This is where the picture gets more complex, and where the "it's just peer-to-peer, nothing leaves" argument breaks down.
A. Demand shifts away from fiat
Even if individual P2P trades do not remove fiat from the country, the preference shift matters at scale. If millions of Sri Lankans start preferring USDT over LKR as their savings vehicle, demand for LKR falls. That weakens the currency's fundamentals, not through any single transaction but through aggregate behavior: a slow, informal dollarization outside the banking system's view.
B. Capital flight: when USDT trading in Sri Lanka sends value abroad
Here is the scenario where real economic value exits the country:
- Economic value exited Sri Lanka. Purchasing power was exported.
- Pressure on foreign reserves increases.
- The import and export imbalance worsens.
No physical cash crossed a border, yet purchasing power left. The rupees Person A spent are still in Person B's hands, but the economic value they represent has moved to a foreign jurisdiction.
C. Banking liquidity changes
A third, slower mechanism worries regulators most. If people stop saving in banks and hold stablecoins instead, the banking system changes in measurable ways:
// Section 04
Why governments get concerned
It is worth being precise about what governments are and are not worried about, because the popular narrative often conflates the two.
Small peer-to-peer swaps between citizens holding USDT locally. These do not directly affect national reserves or the money supply in the short term.
Loss of monetary sovereignty. The inability to monitor economic flows, tax leakage on unreported crypto gains, sanctions evasion through borderless transfers, unofficial dollarization that reduces central bank control, and the gradual erosion of fiat in daily economic life.
Central banks work by controlling liquidity, setting interest rates, managing bank reserves and influencing currency demand. Stablecoins partly bypass all of those mechanisms, not by breaking them, but by routing activity around them.
// Section 05
The casino analogy
A classic economics analogy maps closely to what USDT is doing in economies like Sri Lanka's, and it clarifies both the opportunity and the risk.
Imagine a casino operating inside a country. People exchange fiat for chips. The chips circulate heavily, in games, bets and transfers between players, while the underlying fiat mostly stays in the casino's vault. People operate in a secondary economy of chips that is anchored by, but partly detached from, the national fiat system.
USDT often works the same way. It circulates faster and more freely than fiat, while fiat anchors the entry and exit points. The critical difference: casino chips cannot leave the building. USDT can cross borders in seconds, without anyone's permission, to anywhere on earth.
That is what makes stablecoins fundamentally different from earlier parallel currency systems, and why the regulatory picture is so complex.
// Section 06
The deeper monetary shift happening globally
Stablecoins like Tether are not just a new financial instrument. They are creating something that did not exist before: a privately operated, internet-native dollar network that runs independently of any government's permission, infrastructure or monetary policy.
People trust USDT more than local banks for savings. Merchants informally accept it for high-value deals. Traders price assets in it rather than local fiat. Remittances increasingly route through it instead of wire transfers, and cross-border payments move in seconds rather than days.
Analysts describe this reality with several frames, each catching a different side of the same thing:
The "Layer 2 on fiat" framing is the most technically accurate, because it captures both the dependence on the underlying fiat system and the increasingly independent behavior of the overlay.
"Crypto trading itself is mostly redistribution of existing fiat between participants. The real macroeconomic effect comes from where the crypto came from, where it exits, and whether it replaces national savings behavior."
// Section 07
So, does USDT trading take money out of Sri Lanka?
Here is the honest, complete answer. It depends on which part of the flow you look at:
The local P2P trade itself does not drain national fiat reserves. What matters is the full journey: where the USDT in circulation originally came from, and where it goes when it leaves the crypto ecosystem.
If USDT circulates within Sri Lanka, bought, sold and held by Sri Lankans, the fiat anchor stays intact. The moment it exits to a foreign counterparty or pays for something abroad, the equation changes. That distinction is the foundation for thinking clearly about crypto policy, personal financial strategy and the role of stablecoins in economies where the informal crypto market has run years ahead of regulation. For the flip side, how the same rails can bring dollars in, see our piece on Sri Lanka's digital dollar economy.
// Section 08 · 2026 update
Sri Lanka crypto regulations in 2026: the rules are coming
That gap is starting to close. On 28 July 2026 the Cabinet approved a proposal naming the Securities and Exchange Commission of Sri Lanka as the regulator for virtual assets and virtual asset service providers. Legislation is now being drafted, with the Central Bank, the Financial Intelligence Unit and the Inland Revenue Department supervising alongside the SEC.
- Mandatory registration for crypto service providers operating in Sri Lanka.
- Reporting standards aimed at the peer-to-peer and offshore trading that runs outside today's rules.
- Taxation mechanisms for digital asset services.
- Alignment with FATF standards on money laundering and terrorist financing.
Cryptocurrencies are not legal tender in Sri Lanka, and as of October 2026 the new law is still being drafted. Until it passes, P2P trading continues through unregulated channels, so keep records of every trade and check the SEC's announcements before relying on any platform.
The question was never whether USDT leaves Sri Lanka. It is which way the dollars flow.
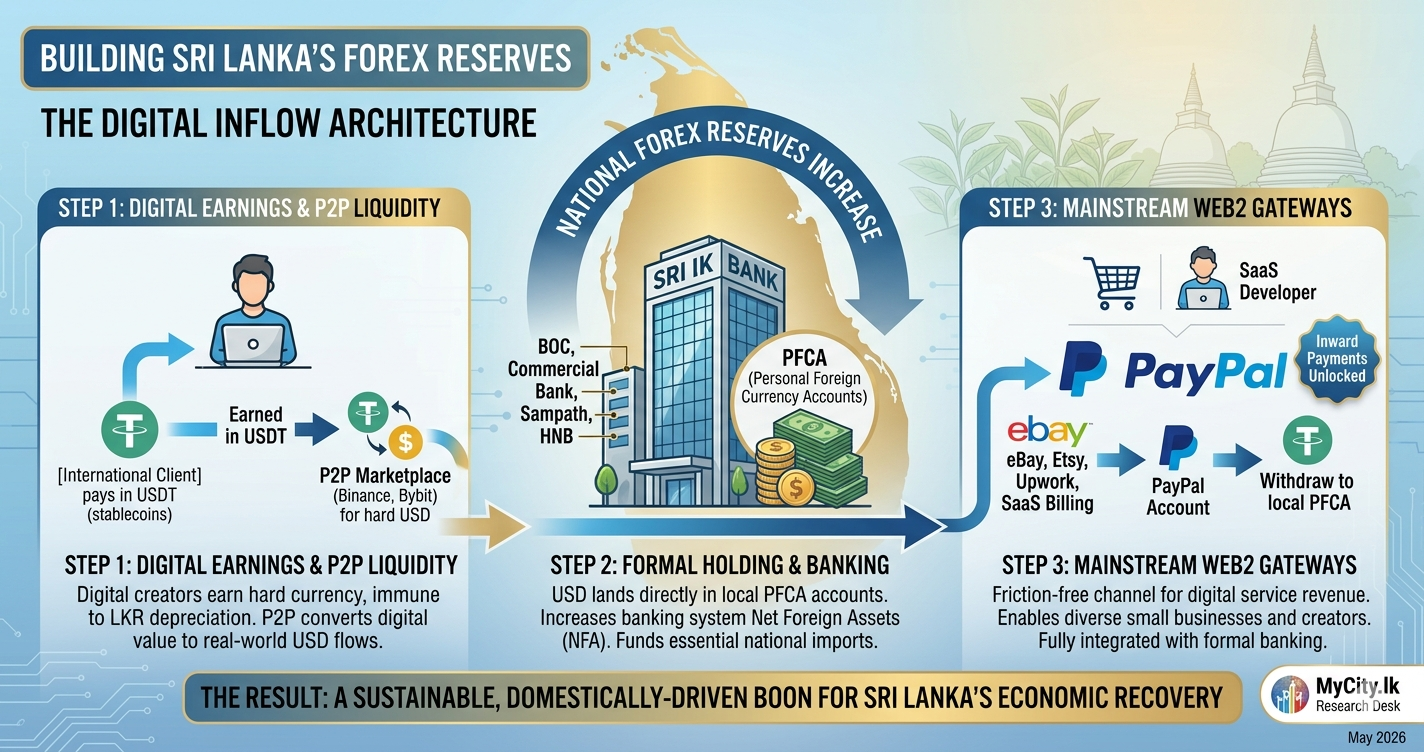
Stablecoins are a rail, and rails run both ways. Used to move savings offshore, they export purchasing power. Used by freelancers, exporters and remote workers to bring income home, the same rail can strengthen the economy. Regulation in 2026 will decide how visible those flows become; understanding the mechanics decides which side of them you are on.
// Common questions
USDT trading in Sri Lanka: frequently asked questions
-
Does buying USDT locally take money out of Sri Lanka?
Not on its own. In a local peer-to-peer trade the rupees simply move from one Sri Lankan bank account to another, so the national fiat supply is unchanged. Value leaves the country only when USDT is sent to a foreign party who cashes it out, which has the same effect as capital flight.
-
Is USDT trading legal in Sri Lanka?
Cryptocurrencies are not legal tender in Sri Lanka and there is no dedicated crypto law yet. In July 2026 the Cabinet named the Securities and Exchange Commission as the regulator for virtual assets, and legislation covering registration, reporting and taxation is being drafted. Until then, trading runs through unregulated channels.
-
Who regulates crypto in Sri Lanka?
The Securities and Exchange Commission of Sri Lanka was named the primary regulator for virtual assets and service providers in July 2026, with the Central Bank, the Financial Intelligence Unit and the Inland Revenue Department supervising jointly.
-
Why do central banks worry about stablecoins?
Because stablecoins route savings and payments around the banking system. That reduces deposits and lending, weakens the effect of interest rate decisions, makes flows harder to monitor and can lead to informal dollarization.
-
What does "USDT as a Layer 2 on fiat" mean?
It describes USDT as a fast, borderless settlement network running on top of the national fiat system. Fiat still anchors the entry and exit points, taxes and salaries, while USDT handles savings, trading and cross-border transfers above it.